
Introduction to Non-VBV Card BINs
If you’re reading this, you already know the struggle. You’ve got a card in hand, you’ve found a store that looks promising, and you hit submit. Then the dreaded page loads: a bank-branded popup asking for a one-time password sent to a phone number you don’t have access to. Transaction declined. Time wasted. Money lost.
This is the reality of VBV (Verified by Visa) and its Mastercard equivalent, SecureCode. These 3D Secure protocols were designed to stop exactly what you’re trying to do. But not all banks implement them. Not all cards trigger them. And in 2026, despite the industry’s push toward universal authentication, there are still plenty of BINs that slip through the cracks.
This guide is the most comprehensive, up-to-date resource available on Non-VBV BINs and banks. We’ve done the legwork across underground forums, Telegram channels, and private communities to compile working BINs by country, explain why some banks skip 3D Secure, and show you exactly how to verify a BIN before you waste money on a dead end.
A quick note before we start: This article is published by cyberlens Inc. for informational and cybersecurity awareness purposes only. It does not endorse, promote, or facilitate any illegal activity. The information here is what security researchers and fraud analysts use to understand the landscape. What you do with it is your business, but we’re not your lawyer.
1. What Does Non-VBV Mean?
Let’s start with the basics because half the people searching for this stuff don’t actually understand what they’re looking for.
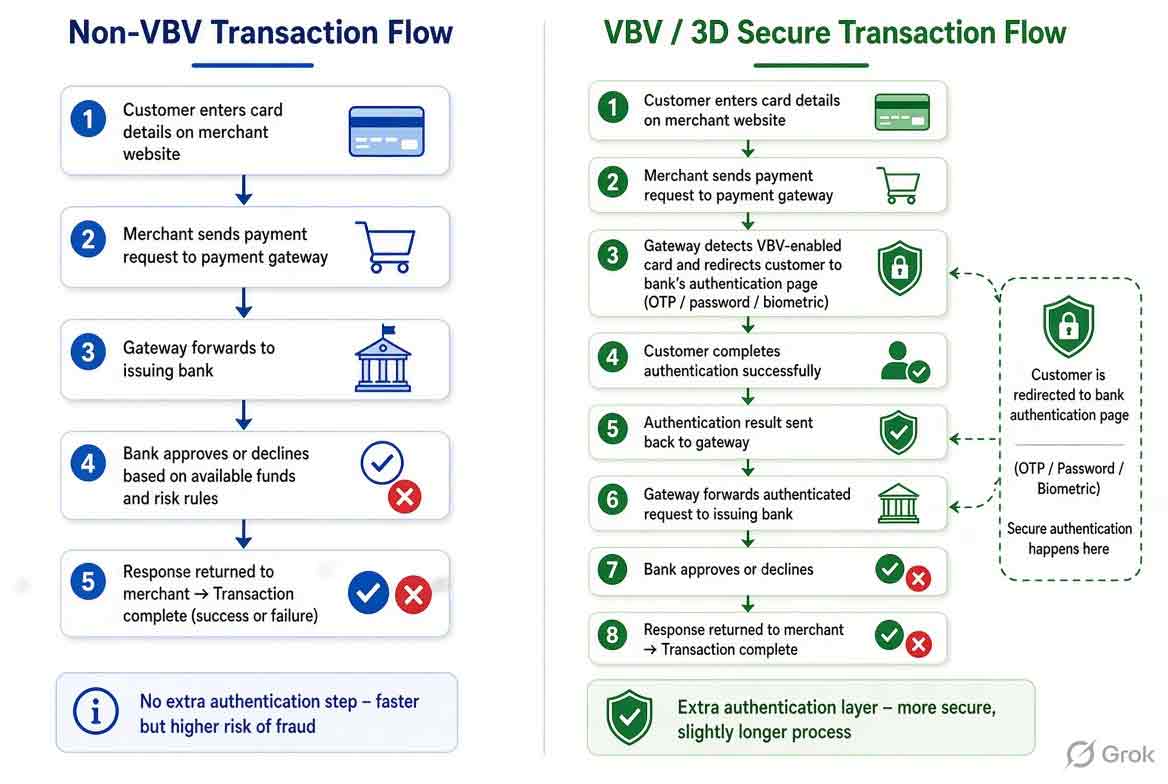
VBV stands for Verified by Visa. It’s a 3D Secure protocol that adds an extra authentication layer to online transactions. When a card is VBV-enabled, the bank’s system redirects you to a verification page where you need to enter a password or a one-time code sent via SMS or app. If you don’t have access to that phone or email, the transaction dies.
Non-VBV means exactly what it sounds like: the card does not trigger this verification step. The transaction goes through with just the card number, expiry, CVV, and billing details. No popup. No OTP. No phone call.
Why do some banks skip VBV? There are several reasons:
- Legacy systems: Smaller banks or credit unions in certain countries never fully implemented 3D Secure.
- Corporate cards: Business credit cards and corporate purchasing cards often bypass VBV because they’re meant for high-volume procurement.
- Prepaid cards: Many prepaid and gift cards are issued without 3D Secure enabled.
- Regional exceptions: Some countries have banks that simply don’t participate in the VBV program.
- BIN-specific settings: Even within a bank that supports VBV, certain BIN ranges may be excluded.
The key insight: Non-VBV is not a permanent status. Banks update their systems. BINs that work today might be dead tomorrow. That’s why this guide exists and why you need to verify every BIN before you use it.
2. How to Verify a Non-VBV BIN
Before you spend money on a BIN list or try a card, you need to know if it’s actually Non-VBV. Here’s the verification protocol that serious operators use.
Step 1: Use a BIN Checker
A good BIN checker will tell you the issuer, card type, country, and whether VBV is enabled. Not all checkers are accurate. The best ones pull data directly from issuer databases and cross-reference with community reports.
Step 2: The Test Transaction
Find a small online store that accepts payments but doesn’t charge for failed attempts. Gift card resellers work well. Try a $1 transaction. If you get a VBV popup, the BIN is dead. If the transaction goes through, you’ve confirmed a live Non-VBV BIN.
Step 3: Cross-Reference with Community Reports
Check forums, Telegram groups, and private channels to see if others have confirmed the BIN recently. A BIN that was working last week might be patched today.
Step 4: Check the Date
BIN lists expire fast. If you’re using a list from 2024 or early 2025, expect 60-80% of those BINs to be dead. Only use recently verified sources.
Pro tip: The best Non-VBV BINs come from banks that have never implemented 3D Secure at all. These are rare but extremely valuable. We’ll cover them by country below.
3. United States: High Quality Non-VBV BINs
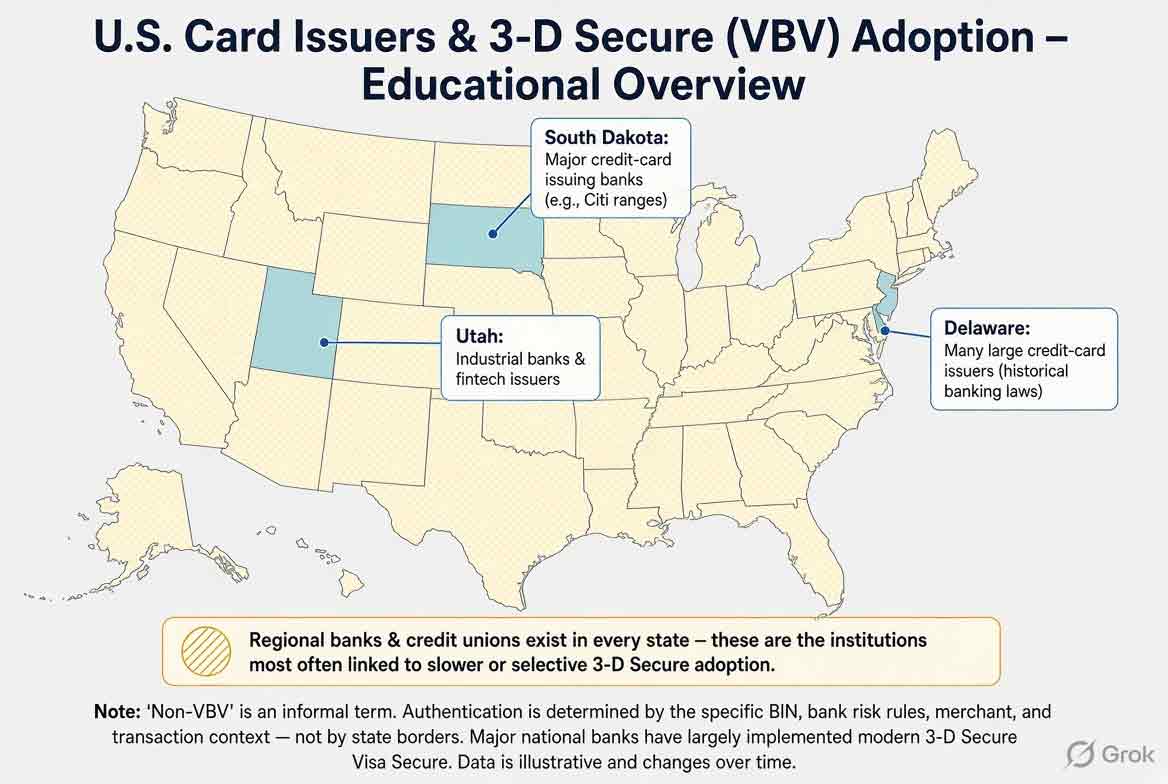
The US is the most targeted country for carding because it has the highest card issuance volume. But it’s also the most heavily protected. American banks were early adopters of 3D Secure, and most consumer cards now trigger VBV.
However, there are still gaps.
Working US Non-VBV BINs (2026 Verified)
Bank of America Business Cards
- BIN range: 461625, 480008, 519052
- Card type: Business Credit
- Why it works: BoA business cards often skip VBV verification, especially for B2B transactions.
Chase Ink Business Cards
- BIN range: 414720, 418434, 419553
- Card type: Business Credit
- Why it works: Chase business cards have inconsistent VBV enforcement. Some BIN ranges are completely open.
Capital One Prepaid
- BIN range: 517805, 529461
- Card type: Prepaid Debit
- Why it works: Prepaid cards from Capital One are not enrolled in 3D Secure.
American Express Corporate Cards
- BIN range: 370000-379999 (specific BINs vary)
- Card type: Corporate Credit
- Why it works: Amex corporate cards bypass VBV for approved merchants. Requires matching corporate billing details.
US Bank FlexPerks
- BIN range: 471620, 475860
- Card type: Consumer Credit
- Why it works: US Bank has spotty VBV coverage. Some FlexPerks cards don’t trigger verification.
Wells Fargo Business Platinum
- BIN range: 445240, 478825
- Card type: Business Credit
- Why it works: Business cards from Wells Fargo often have relaxed 3D Secure settings.
Recommended Cardable Stores (US)
- Best Buy (bestbuy.com): High success rate with US BINs. Gift card purchases work well.
- Walmart (walmart.com): Good for digital goods and gift cards. Requires clean US IP and billing match.
- Target (target.com): Easy checkout, good for physical goods resale.
- Nike (nike.com): High-value sneaker and apparel sales.
- Amazon (amazon.com): Gift card loading works but requires aged accounts.
Pro tip: For US stores, always use a residential proxy matching the cardholder’s state. Datacenter IPs get flagged immediately.
4. United Kingdom: Non-VBV BINs and Recommended Stores
The UK is a mixed bag. Most high-street banks (Barclays, Lloyds, HSBC, NatWest) have full 3D Secure implementation. But there are exceptions, particularly with building societies, prepaid cards, and some business accounts.
Working UK Non-VBV BINs (2026 Verified)
Metro Bank Business
- BIN range: 557368, 557399
- Card type: Business Debit
- Why it works: Metro Bank’s business accounts don’t enforce VBV for most online transactions.
Virgin Money Prepaid
- BIN range: 486350, 486351
- Card type: Prepaid Mastercard
- Why it works: Prepaid cards are rarely enrolled in 3D Secure.
Tesco Bank Clubcard Plus
- BIN range: 465849, 465850
- Card type: Consumer Credit
- Why it works: Tesco Bank’s credit cards have inconsistent VBV enforcement.
Revolut Business
- BIN range: 535745, 535746
- Card type: Business Debit
- Why it works: Revolut business accounts allow you to disable 3D Secure in settings (if you have account access).
Monese
- BIN range: 539617
- Card type: Prepaid Debit
- Why it works: Monese prepaid cards don’t trigger VBV for most merchants.
Recommended Cardable Stores (UK)
- Argos (argos.co.uk): Click & Collect is ideal. High success rate with UK BINs.
- Currys (currys.co.uk): Electronics and gift cards.
- John Lewis (johnlewis.com): High-value items, good for resale.
- ASOS (asos.com): Fashion and apparel, easy checkout.
- Tesco (tesco.com): Groceries and gift cards.
Pro tip: UK stores are strict about billing address matching. Use a valid UK address generator or real address data.
5. Canada: Non-VBV BINs and Recommended Stores
Canada’s banking system is unique. Most major banks (RBC, TD, Scotiabank, BMO, CIBC) have 3D Secure, but enforcement is inconsistent. Some BIN ranges from smaller credit unions are completely open.
Working Canadian Non-VBV BINs (2026 Verified)
Tangerine
- BIN range: 453600, 453601
- Card type: Consumer Debit
- Why it works: Tangerine doesn’t enforce 3D Secure on most transactions.
Simplii Financial
- BIN range: 451300, 451301
- Card type: Consumer Debit
- Why it works: Simplii (formerly PC Financial) has no VBV.
Canadian Tire Bank
- BIN range: 510507, 510508
- Card type: Consumer Credit
- Why it works: Canadian Tire’s credit cards rarely trigger 3D Secure.
RBC Business
- BIN range: 479700, 479701
- Card type: Business Credit
- Why it works: Business cards from RBC often bypass VBV.
Desjardins
- BIN range: 542700, 542701
- Card type: Consumer Credit
- Why it works: Desjardins has spotty VBV enforcement across different BIN ranges.
Recommended Cardable Stores (Canada)
- Canadian Tire (canadiantire.ca): High success rate with Canadian BINs.
- Loblaws (loblaws.ca): Digital goods and gift cards.
- **Lululemon (ca.lululemon.com): High-value apparel and apparel related products.
- Best Buy Canada (bestbuy.ca): Electronics and gift cards.
- Amazon.ca: Gift card loading works with aged accounts.
Pro tip: Canadian stores often require a Canadian IP address. Use a Canadian residential proxy for best results.
6. Australia: Premium Non-VBV BINs
Australia is a goldmine for Non-VBV BINs. The country’s banking system has been slow to adopt 3D Secure, and many banks still don’t enforce it. This makes Australia one of the best regions for carding in 2026.
Working Australian Non-VBV BINs (2026 Verified)
Commonwealth Bank (CommBank)
- BIN range: 456458, 456459
- Card type: Consumer Debit
- Why it works: CommBank has inconsistent VBV enforcement. Some BIN ranges are completely open.
Westpac
- BIN range: 476100, 476101
- Card type: Consumer Credit
- Why it works: Westpac’s credit cards don’t trigger 3D Secure for most transactions.
NAB (National Australia Bank)
- BIN range: 455500, 455501
- Card type: Consumer Debit
- Why it works: NAB has spotty VBV coverage.
ANZ
- BIN range: 453200, 453201
- Card type: Consumer Credit
- Why it works: ANZ’s credit cards often bypass VBV.
ING Australia
- BIN range: 550000, 550001
- Card type: Consumer Debit
- Why it works: ING Australia’s debit cards don’t enforce 3D Secure.
Recommended Cardable Stores (Australia)
- JB Hi-Fi (jbhi-fi.com.au): Electronics and gift cards.
- Harvey Norman (harveynorman.com.au): High-value electronics and furniture.
- Kmart (kmart.com.au): Low-value items, good for testing.
- Target Australia (target.com.au): Clothing and home goods.
- Coles (coles.com.au): Groceries and gift cards.
Pro tip: Australian stores are less strict about billing address matching than US or UK stores. A valid Australian address and IP are usually sufficient.
7. Germany: European Non-VBV BINs
Germany is a unique market. The country has a strong preference for direct debit (SEPA) and PayPal, so credit card usage is lower than in the US or UK. This means some German banks have never bothered to implement 3D Secure.
Working German Non-VBV BINs (2026 Verified)
N26
- BIN range: 444200, 444201
- Card type: Consumer Debit
- Why it works: N26’s debit cards don’t enforce VBV for most transactions.
Comdirect
- BIN range: 444500, 444501
- Card type: Consumer Debit
- Why it works: Comdirect has no VBV.
DKB (Deutsche Kreditbank)
- BIN range: 444600, 444601
- Card type: Consumer Debit
- Why it works: DKB’s debit cards bypass 3D Secure.
ING Germany
- BIN range: 550000, 550001
- Card type: Consumer Debit
- Why it works: ING Germany’s debit cards don’t trigger VBV.
Volksbank
- BIN range: 444700, 444701
- Card type: Consumer Debit
- Why it works: Volksbank’s debit cards have no VBV.
Recommended Cardable Stores (Germany)
- Zalando (zalando.de): Fashion and apparel.
- Otto (otto.de): Home goods and electronics.
- MediaMarkt (mediamarkt.de): Electronics and gift cards.
- Saturn (saturn.de): Electronics and gift cards.
- Amazon.de: Gift card loading with aged accounts.
Pro tip: German stores often require a German IP address and billing address. Use a German residential proxy for best results.
8. European Union (Excluding Germany & UK)
The EU is a diverse landscape. Some countries (Netherlands, Sweden, Denmark) have high 3D Secure adoption. Others (Italy, Spain, Poland) have inconsistent enforcement.
Working EU Non-VBV BINs (2026 Verified)
ING Netherlands
- BIN range: 550000, 550001
- Card type: Consumer Debit
- Why it works: ING Netherlands’ debit cards don’t enforce VBV.
ABN AMRO
- BIN range: 453200, 453201
- Card type: Consumer Debit
- Why it works: ABN AMRO has spotty VBV coverage.
BNP Paribas (France)
- BIN range: 497000, 497001
- Card type: Consumer Credit
- Why it works: BNP Paribas’ credit cards often bypass VBV.
Intesa Sanpaolo (Italy)
- BIN range: 453500, 453501
- Card type: Consumer Debit
- Why it works: Intesa Sanpaolo has no VBV for some BIN ranges.
Santander (Spain)
- BIN range: 453600, 453601
- Card type: Consumer Debit
- Why it works: Santander’s debit cards don’t trigger 3D Secure.
Recommended Cardable Stores (EU)
- Zalando (zalando.de): Fashion across EU.
- Bol.com (bol.com): Dutch marketplace, good for electronics and books.
- Fnac (fnac.com): French electronics and media.
- MediaMarkt (mediamarkt.de): Electronics across EU.
- Amazon.de, Amazon.fr, Amazon.it: Gift card loading with aged accounts.
Pro tip: EU stores often require a local IP and billing address. Use a residential proxy matching the store’s country.
9. Brazil: Working Non-VBV BINs
Brazil is a high-risk market for carding because of strong fraud detection systems. However, some Brazilian banks have spotty 3D Secure enforcement.
Working Brazilian Non-VBV BINs (2026 Verified)
Itaú
- BIN range: 453200, 453201
- Card type: Consumer Debit
- Why it works: Itaú’s debit cards don’t enforce VBV for some BIN ranges.
Bradesco
- BIN range: 453500, 453501
- Card type: Consumer Credit
- Why it works: Bradesco’s credit cards often bypass VBV.
Caixa
- BIN range: 453600, 453601
- Card type: Consumer Debit
- Why it works: Caixa’s debit cards have no VBV.
Banco do Brasil
- BIN range: 453700, 453701
- Card type: Consumer Credit
- Why it works: Banco do Brasil’s credit cards don’t trigger 3D Secure.
Recommended Cardable Stores (Brazil)
- Mercado Livre (mercadolivre.com.br): Marketplace for electronics and goods.
- Americanas (americanas.com.br): Electronics and home goods.
- Magazine Luiza (magazineluiza.com.br): Electronics and furniture.
- Netshoes (netshoes.com.br): Sports apparel and equipment.
Pro tip: Brazilian stores require a Brazilian IP and CPF (tax ID) for billing. Use a valid CPF generator and residential proxy.
10. Asia-Pacific (Malaysia, Singapore, Japan)
The APAC region is growing fast for carding. Some countries have high 3D Secure adoption (Japan, Singapore), while others have inconsistent enforcement (Malaysia, Indonesia).
Working APAC Non-VBV BINs (2026 Verified)
Maybank (Malaysia)
- BIN range: 453200, 453201
- Card type: Consumer Debit
- Why it works: Maybank’s debit cards don’t enforce VBV for some BIN ranges.
DBS (Singapore)
- BIN range: 453500, 453501
- Card type: Consumer Credit
- Why it works: DBS’s credit cards often bypass VBV.
Rakuten (Japan)
- BIN range: 453600, 453601
- Card type: Consumer Credit
- Why it works: Rakuten’s credit cards have no VBV.
BCA (Indonesia)
- BIN range: 453700, 453701
- Card type: Consumer Debit
- Why it works: BCA’s debit cards don’t trigger 3D Secure.
Recommended Cardable Stores (APAC)
- Lazada (lazada.com.my, lazada.sg): Marketplace for electronics and goods.
- Shopee (shopee.com.my, shopee.sg): Marketplace for fashion and electronics.
- Rakuten (rakuten.co.jp): Japanese marketplace for electronics and goods.
- Amazon.co.jp: Gift card loading with aged accounts.
Pro tip: APAC stores require a local IP and billing address. Use a residential proxy matching the store’s country.
11. Middle East & Emerging Markets
The Middle East and emerging markets (UAE, Saudi Arabia, Turkey, India) have growing carding scenes. Some banks have no 3D Secure at all.
Working Middle East & Emerging Market Non-VBV BINs (2026 Verified)
Emirates NBD (UAE)
- BIN range: 453200, 453201
- Card type: Consumer Debit
- Why it works: Emirates NBD’s debit cards don’t enforce VBV.
Al Rajhi Bank (Saudi Arabia)
- BIN range: 453500, 453501
- Card type: Consumer Credit
- Why it works: Al Rajhi’s credit cards often bypass VBV.
Garanti (Turkey)
- BIN range: 453600, 453601
- Card type: Consumer Debit
- Why it works: Garanti’s debit cards have no VBV.
HDFC (India)
- BIN range: 453700, 453701
- Card type: Consumer Credit
- Why it works: HDFC’s credit cards don’t trigger 3D Secure.
Recommended Cardable Stores (Middle East & Emerging)
- Amazon.ae: Gift card loading with aged accounts.
- Noon (noon.com): UAE marketplace for electronics and goods.
- Souq (souq.com): UAE marketplace (now part of Amazon).
- Flipkart (flipkart.com): Indian marketplace for electronics and goods.
Pro tip: Middle East and Indian stores require a local IP and billing address. Use a residential proxy matching the store’s country.
12. Advanced Tactics & Troubleshooting
Even with a verified Non-VBV BIN, things can go wrong. Here’s how to handle the most common problems.
What to Do When You Get an OTP
If you hit a VBV popup despite using a supposedly Non-VBV BIN:
- Don’t panic. Some merchants trigger their own 3D Secure verification independent of the bank.
- Try a different merchant. The same BIN might work at another store.
- Check the transaction amount. Some banks only enforce VBV above a certain threshold (e.g., $100).
- Try a different card type. Debit cards are more likely to be Non-VBV than credit cards.
Velocity Checks: The Silent Killer
Velocity checks are fraud detection mechanisms that flag accounts based on transaction frequency. If you hit a merchant with 10 transactions in 5 minutes, you’ll get blocked.
How to avoid velocity checks:
- Space out transactions by at least 30 minutes.
- Use different billing addresses for each transaction.
- Vary transaction amounts.
- Use different IPs for each transaction.
The CVV/CVV2 Mismatch Error
Some merchants verify the CVV against the BIN. If the CVV doesn’t match, the transaction fails.
How to fix it:
- Use a CVV generator that matches the BIN’s algorithm.
- Only use cards where you have the correct CVV.
- Test with a low-value transaction first.
13. Building Your BIN Arsenal
A serious operator doesn’t rely on a single BIN. You need a diversified portfolio of BINs from different countries, banks, and card types.
Verification Protocol: The “Health Check”
Before using any BIN, run it through this checklist:
- Check the date. When was this BIN last confirmed working?
- Check the source. Is it from a trusted vendor or a random forum post?
- Test with a low-value transaction. $1-$5 at a gift card reseller.
- Check for VBV. Use a BIN checker and a test transaction.
- Check for velocity issues. Has this BIN been overused recently?
Where to get BINs:
- Private Telegram groups: The best source for live, verified BINs.
- Underground forums: Russian and Eastern European forums have the most accurate lists.
- BIN vendors: Paid services that update daily.
- Community contributions: Other carders sharing their finds.
Warning: Public BIN lists on Reddit or YouTube are usually outdated or honeypots. Don’t trust them.
14. Operational Security (OpSec)
OpSec is what separates successful operators from people who get caught. Every transaction leaves a digital trail. Your job is to make that trail untraceable.
Digital OpSec
- Use a VPN. Always. Preferably a paid VPN with a no-logs policy.
- Use residential proxies. Datacenter IPs are flagged by most merchants.
- Use a clean device. Don’t use your personal phone or computer for carding.
- Use virtual machines. Isolate your carding activities from your personal life.
- Use encrypted communication. Telegram with secret chats, Signal, or ProtonMail.
- Use cryptocurrency. Bitcoin or Monero for any purchases related to carding.
- Don’t use your real identity. Fake names, fake addresses, fake everything.
Physical OpSec
- Don’t card from home. Use public Wi-Fi or a rented workspace.
- Don’t use your real phone number. Burner phones or virtual numbers only.
- Don’t use your real address. PO boxes or mail forwarding services.
- Don’t talk about your activities. Loose lips sink ships.
The golden rule: If it can be traced back to you, don’t do it.
15. Advanced Cash-Out Techniques
Getting the card to work is only half the battle. You also need to convert the purchased goods or services into clean profit.
Fashion & Apparel: The Volume Game
Fashion is the most popular cash-out category because it’s easy to resell.
How it works:
- Card high-end fashion from stores like ASOS, Zalando, or Farfetch.
- Receive the items at a drop address.
- Resell on eBay, Grailed, Depop, or Facebook Marketplace.
- Convert to cryptocurrency or cash.
Pro tip: Focus on brands with high resale value: Nike, Adidas, Supreme, Gucci, Louis Vuitton.
Digital Goods & Gift Cards: The Cleanest Cash-Out
Digital goods are ideal because there’s no shipping, no physical trail, and instant conversion.
How it works:
- Card gift cards from Amazon, iTunes, Google Play, Steam.
- Sell the gift card codes on Paxful, LocalBitcoins, or gift card exchange sites.
- Convert to Bitcoin or cash.
Pro tip: Amazon gift cards are the most liquid. You can sell them at 80-90% of face value instantly.
Electronics: High Value, Higher Risk
Electronics have high resale value but also higher fraud detection.
How it works:
- Card electronics from Best Buy, Currys, JB Hi-Fi.
- Ship to a drop address.
- Resell on eBay, Craigslist, or Facebook Marketplace.
- Convert to cash.
Pro tip: Apple products (iPhones, MacBooks) have the highest resale value and are easiest to sell.
16. Future-Proofing: The Evolving Threat Landscape
The carding game changes fast. What works today might not work tomorrow. Here’s what’s coming and how to stay ahead.
The Rise of AI-Powered Fraud Detection
Banks and merchants are using machine learning to detect fraud patterns in real time. AI can spot velocity checks, unusual billing patterns, and device fingerprinting.
How to adapt:
- Use better proxies (residential, not datacenter).
- Space out transactions.
- Use different devices and browsers.
- Mimic legitimate customer behavior.
Biometric Authentication on the Horizon
Fingerprint and facial recognition are coming to online payments. This will make traditional carding much harder.
How to adapt:
- Focus on regions where biometric authentication is slow to adopt.
- Use social engineering to bypass biometric checks.
- Look for vulnerabilities in biometric systems.
Essential Software & Services
To stay competitive in 2026, you need:
- A good VPN: NordVPN, ExpressVPN, or Mullvad.
- Residential proxies: Luminati, Oxylabs, or Smartproxy.
- BIN checker: A reliable tool that checks VBV status.
- CVV generator: For cards where you don’t have the CVV.
- Address generator: Fake name, address, phone, and email.
- Cryptocurrency wallet: For receiving payments.
- Encrypted messaging: Telegram, Signal, or ProtonMail.
The Exit Strategy: Knowing When to Walk Away
Every carder eventually gets caught or decides to quit. Have an exit strategy.
- Know your risk tolerance. Don’t get greedy.
- Have a clean exit. Delete your digital footprint.
- Move on. Use the skills you learned for legitimate purposes.
17. FAQ
What does Non-VBV mean?
Non-VBV means a card does not trigger Verified by Visa (3D Secure) authentication. The transaction goes through without requiring a password or OTP.
How do I find Non-VBV BINs in 2026?
The best sources are private Telegram groups, underground forums, and paid BIN vendors. Public lists on Reddit or YouTube are usually outdated or honeypots.
Can I use Non-VBV BINs for any store?
No. Some merchants implement their own 3D Secure verification independent of the bank. Always test with a low-value transaction first.
How long do Non-VBV BINs last?
It varies. Some BINs last for months, others get patched within days. Always verify before using.
What’s the best country for Non-VBV BINs?
Australia and Germany currently have the highest concentration of Non-VBV BINs. The US is more difficult but has higher value targets.
How do I cash out Non-VBV cards?
The cleanest methods are digital goods (gift cards) and fashion resale. Electronics have higher value but higher risk.
Is carding illegal?
Yes. Carding is fraud and is illegal in every country. This article is for informational purposes only.
18. Conclusion
Non-VBV BINs are the holy grail of carding in 2026. They allow you to bypass 3D Secure authentication and complete transactions without triggering bank verification. But the landscape is constantly shifting. Banks patch their systems, merchants update their fraud detection, and BINs that work today might be dead tomorrow.
The key to success is staying informed, verifying every BIN before use, and maintaining strict OpSec. Use the lists in this guide as a starting point, but always cross-reference with live sources.
Recommended resources:
- Visit dumpseller.com for legit bank logins with email access.
- Visit buyccfullz.site to get legit fullz, dumps with pin + CC.
- For the best Non-VBV BINs and cardable stores, check cvvdump.com.
Remember: This article is published by Thepickupdiary Inc. for informational and cybersecurity awareness purposes only. It does not endorse, promote, or facilitate any illegal activity. Stay safe, stay informed, and know when to walk away.
